By Richie Lennon
Treating marketing as a financial decision means connecting spend to net sales, contribution, customer payback and cash. For an e-commerce business, a strong advertising dashboard does not prove the orders are profitable or the next campaign is affordable. Reconcile sales and costs, measure what remains after fulfilment and acquisition, and decide how much cash you can commit before increasing the budget. The aim is a marketing plan the business can fund and measure.
We keep coming back to a simple question: who owns the sale? Meta can claim it. Google can claim it. Email can claim it too. Add every platform’s attributed revenue together and you can end up with more sales than the shop actually made.
That makes a tidy return-on-ad-spend figure a poor substitute for the whole business picture. It tells you something about the platform’s attribution model. It does not tell you whether the business has made money.
Start with sales you can reconcile
Use net sales excluding VAT and after discounts and refunds. Tie the sales-channel records back to your accounting records. Keep settlement deductions separate: the amount Shopify, Stripe or a marketplace pays into the bank is not the sales figure.
Then bring in the costs that make the order possible: products, packaging, fulfilment, delivery subsidies, payment and marketplace fees, and returns. Assign costs consistently. A returned item should not leave the original sale and margin untouched in the report.
An app can make this easier, but it cannot repair the commercial logic automatically. Wrong product costs, missing refunds or inaccurate shipping bands produce confident-looking reports with the wrong answer. That is an accounting and operations problem before it is a dashboard problem.
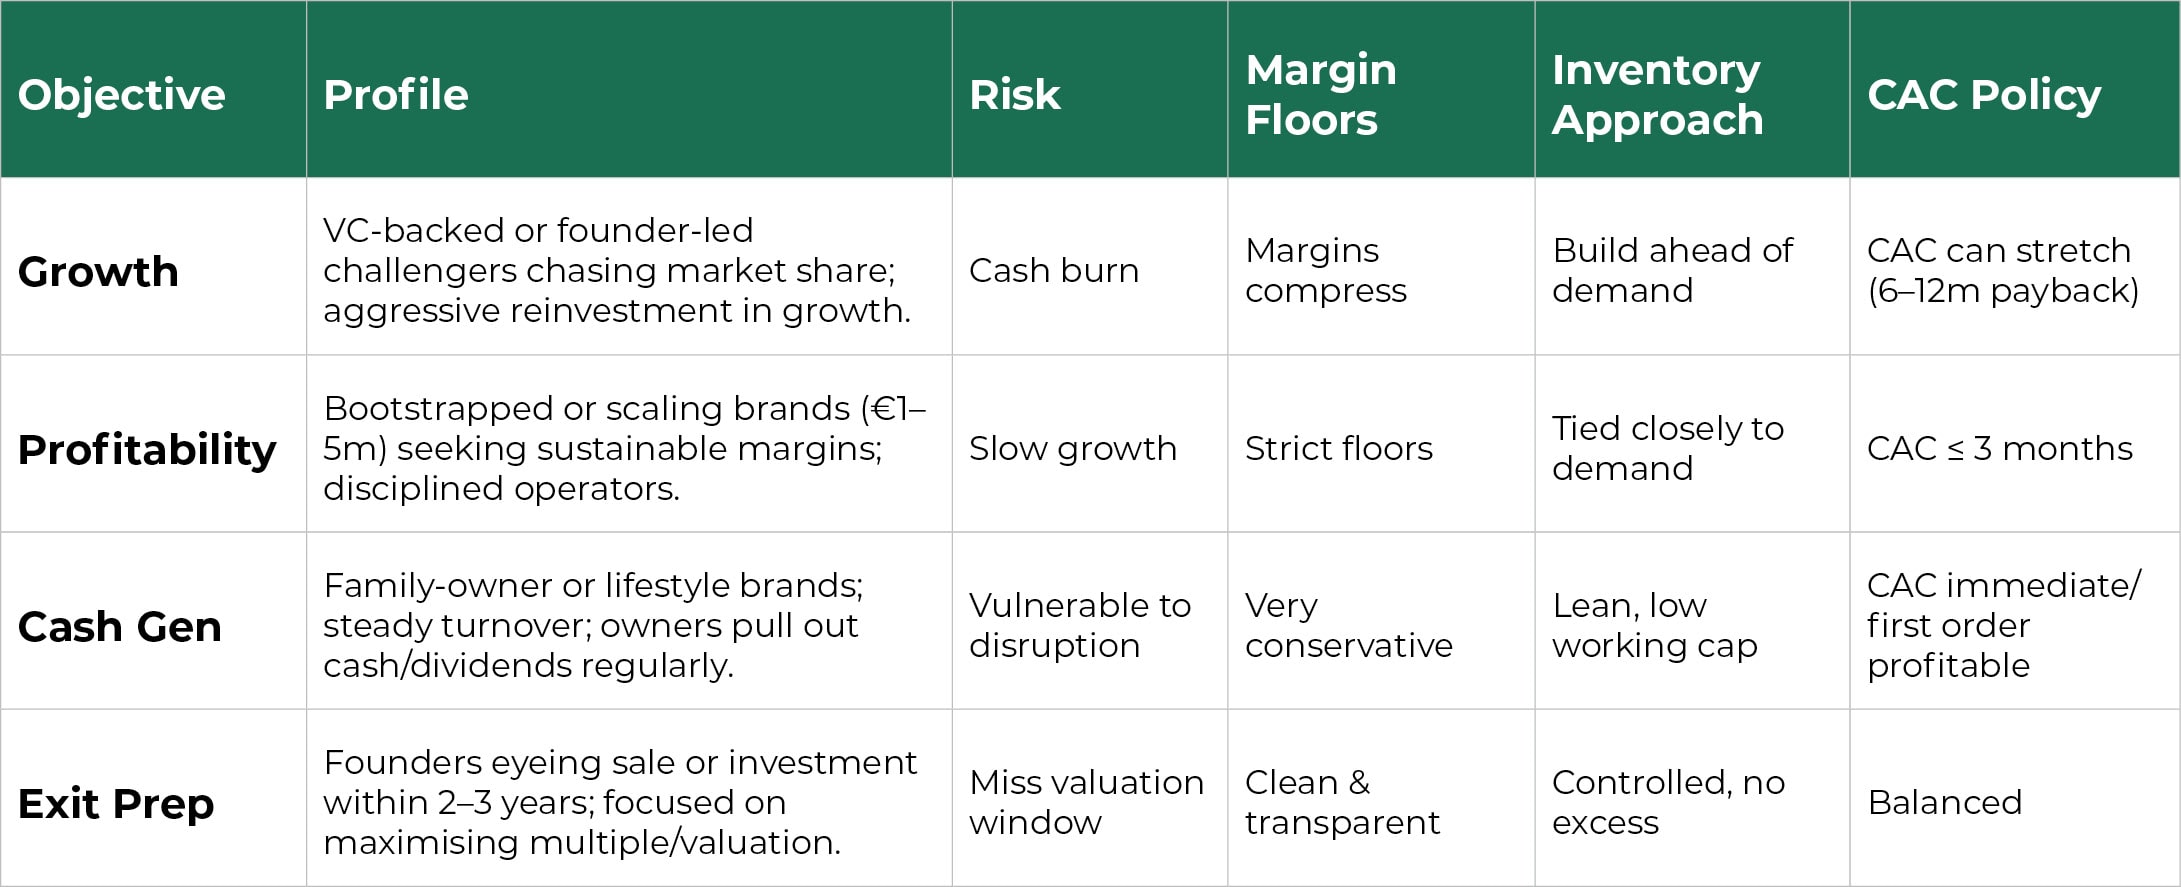
Separate four questions the budget must answer
| Question | Useful measure | What it helps you decide |
|---|---|---|
| Are orders profitable? | Contribution after variable costs and marketing | Whether sales leave money for overheads |
| What does a new customer cost? | Defined acquisition spend divided by new customers | Whether acquisition is affordable |
| When does acquisition pay back? | Cumulative cohort contribution against acquisition cost | How long cash stays committed |
| Can we fund the next push? | Cash forecast including stock, tax and repayments | The budget and timing you can sustain |
Our contribution-margin guide explains the order economics. This article takes the next step: using those numbers to set and review the marketing budget.
What a 5x return can hide
Consider one month’s trading, excluding VAT. Sales are net of discounts and refunds. The figures are illustrative.
| Trading bridge | Amount |
|---|---|
| Net sales | €100,000 |
| Product cost | (€40,000) |
| Fulfilment and delivery cost | (€10,000) |
| Payment and marketplace fees | (€3,000) |
| Contribution before marketing | €47,000 |
| Marketing spend | (€20,000) |
| Contribution after marketing | €27,000 |
| Fixed overheads | (€25,000) |
| Operating result before finance costs and tax | €2,000 |
Revenue divided by marketing spend is 5: €100,000 ÷ €20,000. Here we call that the marketing efficiency ratio, or MER, using net sales and the stated marketing spend. It is a whole-business ratio, not proof that the adverts caused every sale.
The business has a 27% contribution after marketing and a 2% operating result before finance costs and tax. It also still has to fund stock and payment timing. “We are doing 5x” is not enough information to double the budget.
For a platform-specific ratio, see how ROAS is calculated. Always state the revenue basis, spend included and attribution window when comparing reports.
Measure payback through contribution
Customer acquisition cost is acquisition spend divided by the number of new customers acquired under your stated method. Lifetime value needs a definition too: revenue per customer is different from contribution per customer.
Suppose acquisition costs €30 and the first order leaves €18 before acquisition spend. You are €12 short of recovering that acquisition cost. If a later order contributes €15 without another acquisition charge, cumulative contribution reaches €33 and covers the original €30.
That is a useful illustration only if the repeat order actually happens. Check groups of customers acquired in the same period, known as cohorts, at consistent intervals. Include returns and the cost of retention activity. Do not fund today’s orders with an optimistic lifetime value that has not appeared in your customer history.
For a bootstrapped business, first-order contribution matters because the business must survive long enough to earn the later orders. A profitable customer relationship over a year can still create a cash problem this month.
Put stock and payment dates in the same plan
Marketing can generate orders faster than the business can finance them. More sales may require deposits, stock replenishment and fulfilment before the cash becomes available.
Build a cash-flow forecast that includes those dates, VAT, payroll and any funding deductions. Keep a growth target separate from the receipts you use to make commitments.
If considering revenue-linked funding, compare the fee and repayment pattern with your contribution and cash timing. Borrowing does not fix an unprofitable order. Neither does a discount that lifts conversion while removing the margin that pays for acquisition.
Set a budget rule you can act on
Agree the budget, the review date and what would cause you to reduce, hold or increase spend. Base the decision on reconciled contribution, observed customer behaviour and available cash, rather than a universal target such as “every business needs 3x ROAS”.
A practical monthly review should produce decisions: which products to promote, which offer to change, whether to replenish stock and how much cash to commit. Name the person responsible and when the change will happen.
Tools such as StoreHero can help bring the trading view together. Our view is that the tool is useful only when the underlying cost and sales data are reliable. Keep the bookkeeping and the commercial report connected, with a clear owner for discrepancies.
Marketing value is different from an accounting asset
A campaign can create valuable customer relationships without becoming an asset in the accounts. Under FRS 102, advertising and promotional expenditure is generally an expense when incurred; a prepayment for services not yet received is different. Future customer value does not, by itself, justify capitalising an advertising campaign. FRS 102 Section 18 sets out the treatment.
Connect the marketing plan to the finance work
Our e-commerce accounting service connects reconciled sales, costs, cash commitments and VAT with the monthly reporting. Agree any additional commercial analysis in the service scope.
If you run an Irish business turning over €250,000 or more and want the finance behind your growth decisions made clearer, book a Finance Fit Call.
FAQs
What does financialisation of marketing mean here?
It means treating marketing spend as a business decision with measurable sales, contribution, payback and cash consequences. It is not a rule for recording campaigns as assets.
Are ROAS and marketing ROI the same?
No. ROAS compares attributed revenue with advertising spend. A profit-based return needs the relevant costs deducted and its method stated. Revenue alone is not profit.
What MER should my shop target?
There is no universal answer. Your product margin, fulfilment, fees, overheads, customer mix and cash needs determine what is sustainable. Compare ratios calculated on the same basis.
Can software fix inaccurate profit reporting?
It can help process the data, but wrong product costs or missing refunds still give the wrong result. Reconcile and maintain the inputs.
Should I scale before acquisition pays back?
Only with a credible payback case and enough cash to fund the gap. Use observed cohort contribution and a downside forecast rather than assuming every first-time customer will return.