By Richie Lennon ACA
Support and programme information checked 15 October 2026.
At a glance
Irish startup funding can come from founder money, grants, loans, angels and venture capital. Choose it around what the business needs to prove next. PSSF is convertible investment, not a grant. Before signing, model when the cash arrives and what everyone will own after new shares, converting notes and any employee pool.
You can build a product, raise money and still have very little evidence that you have a business.
From the first idea through seed and beyond, keep three questions in view: what will the money achieve, how long will it last and what will you own afterwards?
In this guide
1. Problem–solution fit. Product–market fit. Then scale.
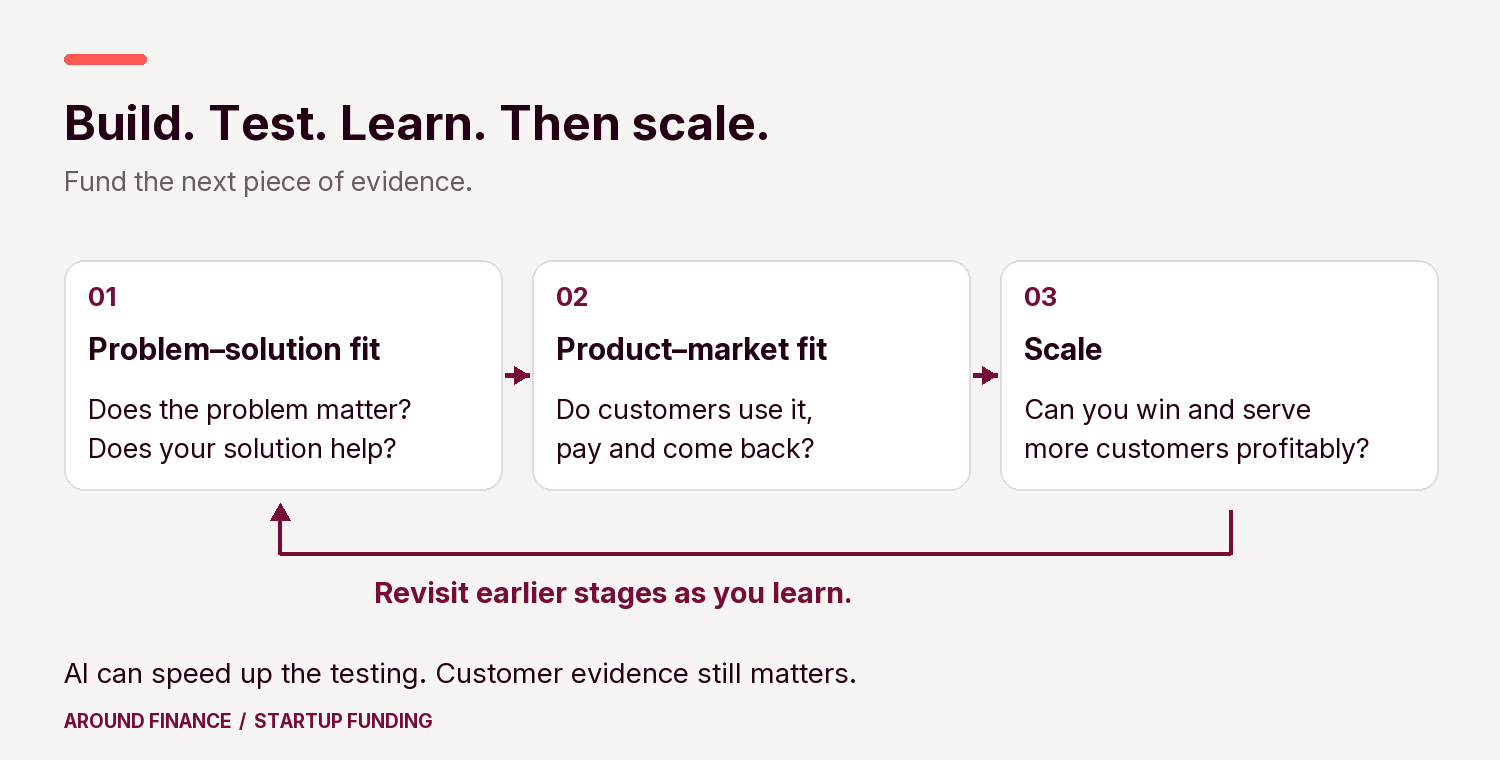
Three stages help you decide what to work on and what to fund:
- Problem–solution fit. Find a problem people need solved and test whether your solution helps. Who has the problem, how do they deal with it now and will they pay for a better answer?
- Product–market fit. Show that people actually want the product. They use it, pay for it and come back. Look for evidence beyond the first few enthusiastic conversations.
- Scale. Work out how to win and serve more customers, with costs and margins that support growth.
AI can make building, testing and changing a product much faster. You can put something in front of customers quickly and learn from what they do. A working product can still be untested commercially.
For a business product, speak to the person who will use it and the person who controls the budget. They may be different people. Find out how buying it would actually get approved.
You may move back and forth between these stages. Early investment can fund the search for product–market fit. The expensive mistake is scaling before you have evidence that the model works. More developers, salespeople and advertising can burn cash and time without solving that problem.
An MVP, a minimum viable product, helps you test that before committing to a full build. It might be a prototype, a paid pilot or a service you initially deliver manually.
Before building it, decide what you need to learn: whether the problem matters, whether someone will pay or whether you can reach the buyer. Set out what result would make you change the plan. That is central to Steve Blank’s approach to testing a business idea.
Build. Test. Learn. Use what you learn to change the product or decide whether to continue. That is the thinking behind Lean Startup’s build–measure–learn loop.
When you ask for funding, explain what the money will prove. Will it get you to repeat paying customers, a sales process you can repeat or a technical milestone? Show why that progress should leave you able to fund the business from trading or make a credible case for the next investment.
Price that work, including your own pay. If you can get there with customer cash and founder resources, bootstrapping may be enough. If you need outside money, work out how much and why.
Record founder money properly from the start. A loan to the company and money paid for shares have different consequences when investors arrive.
Startup programmes: support while you build
New Frontiers is Enterprise Ireland’s nationwide founder-development programme, delivered through third-level institutions at 18 locations.
Phase 1 is part-time, so you can test the idea while staying in employment. Phase 2 requires six months full-time. It currently includes a €17,500 tax-free allowance, subject to eligibility and satisfactory performance, with no equity taken.
Put that allowance beside your household bills before leaving a salary.
Check the funding interactions before assuming you can combine the allowance with other supports. In particular, accepting a PSSF offer ends the New Frontiers allowance, although you may continue on the programme.
Dogpatch Labs in Dublin, PorterShed in Galway and Republic of Work in Cork also deliver or host founder programmes, mentoring and investor-readiness support. These are separate offers from New Frontiers. Check the current programme, intake, time commitment and any equity terms.
For informal peer conversations, there is Baseline and Founder Filter. Furthr also provides structured preparation.
Bring a specific problem: finding a co-founder, testing pricing, getting access to customers or preparing a raise. You do not need to join every programme to build a business.
Choose the person before agreeing the percentage
Getting a co-founder on board is like selling the upstairs bedroom to someone. You will have to live with this person, so you need to be sure.
A useful skill set is part of it. You also need to know how you work together when money is tight, a customer says no or you disagree about what happens next. Work together on something real before making a permanent ownership commitment.
Agree founder roles, time commitments, ownership and how decisions are made.
Be clear about what happens to the shares if a co-founder leaves. If you split the business 50:50 and one person leaves after six months, do they keep half while you spend the next five years building it? Leaving the job does not automatically mean giving up the shares.
Agree founder vesting and leaver terms at the start: which shares they can keep, which they must offer for sale, who can buy them, how the price is calculated and when payment is due. Define what counts as a good or bad leaver. Do not leave those labels for an argument later.
Have your solicitor put an arrangement in place that can actually be carried out. A purchase by the remaining founder and a buyback by the company are different transactions, with different legal, tax and funding consequences. Do not assume the company will have the cash to buy someone out.
Also confirm that the company owns or has the rights it needs to the product and other intellectual property, including work done by contractors. Leaving that until an investor asks can delay the round.
Get the story clear before making the slides
Explain what the business does, who needs it, what you have learned and why your team can deliver. Then say how much you are raising and what it will achieve.
Eamon Leonard’s Baseline deck guide is useful here. At pre-seed, progress can be a prototype tested with customers or an assumption you have proved wrong and acted on. Be clear about what happened.
The deck opens the conversation. Have the figures ready for the next one.
Check what is available now
Enterprise Ireland launched Startup Ireland on 13 October 2026, with a national accelerator pathway, a planned National Startup Hub and an AI accelerator delivered by Dogpatch Labs. The announced company accelerator includes €100,000 investment; the AI programme offers non-equity support.
Check the current intake and terms. Cloud credits can reduce a bill; they cannot pay your employees.
Irish startup grants and loans to check before selling shares
You may need €15,000 to test an idea rather than €500,000 to build a team. Start with the work and check which support fits.
| Route | What it can help with | What to check first |
|---|---|---|
| LEO Feasibility Study Grant | Investigating market demand and technical viability, including eligible prototype and consultancy work. | Whether your project and sector qualify, which costs are covered and the contribution you must fund. |
| LEO Priming Grant | Eligible startup costs during the first 18 months, potentially including equipment, salaries and consultancy. | Business eligibility, the approved spending and job-creation plan. It funds part of eligible costs. |
| Microfinance Ireland Start-Up Loan | Loans of €5,000–€50,000 for qualifying businesses starting up or operating for less than 18 months that have difficulty getting finance elsewhere. | Repayments, affordability and eligibility. You retain your shares, but the business has a debt to service. |
LEO grant support mainly targets qualifying manufacturing and internationally traded services. A local retail or professional-services business should not assume it qualifies because it is new. Ask your LEO before committing spending.
Grant approval and payment are separate steps. You may need to pay the cost before claiming the approved grant, so budget your contribution and that cash gap.
Other routes belong in the plan too
A bank loan may suit spending the business can repay from trading. Put the interest, repayments and any security alongside the cash forecast.
For qualifying technical work, Innovation Vouchers help businesses work with approved knowledge providers. For research-heavy projects, investigate the relevant EIC Accelerator or Horizon Europe call. Those are specialist routes with their own project and application requirements.
Crowdfunding needs an offer people want to back. A reward or pre-order campaign creates a promise to deliver; equity crowdfunding sells ownership. Budget platform costs and fulfilment before treating the amount raised as money available for development. Our startup crowdfunding guide covers campaign preparation and marketing.
For a project involving a genuine technical challenge, ask Enterprise Ireland about its Research, Development & Innovation Fund. It supports eligible development of new products, services or processes. Routine product development is not automatically R&D.
The separate R&D tax credit has increased from 30% to 35%, generally for accounting periods ending on or after 31 December 2026. That can mean €35,000 on €100,000 of qualifying costs, after deducting grant-funded expenditure. Keep records of the technical uncertainty, work done and costs as you go. Employing developers does not, by itself, establish a claim. Revenue explains the qualifying work and timing.
Budget 2027 also announced an increase in the first-year payment threshold from €87,500 to €105,000, alongside wider subcontracting limits. These are announced changes, with legislation and commencement still to be checked before using them in a cash forecast. Budget statement
Our R&D tax credit guide covers the claim in more detail.
Our Enterprise Ireland funding guide covers agency routes in more detail.
2. PSSF: what will the first investment let you do?
Enterprise Ireland’s Pre-Seed Start Fund, PSSF, offers €50,000 or €100,000 investment to qualifying companies. It comes through a convertible loan note, or CLN: a loan that can turn into shares under its terms.
Work backwards from what the money needs to achieve. How much development, customer testing or hiring will it buy? What position will you be in when it runs out?
Use the current offer documents to establish the payment stages, the cash you need alongside it and how the note converts at a later round.
Our PSSF preparation guide covers the budget, evidence and payment timetable.
You will also hear HPSU, High Potential Start-Up, and the Innovative HPSU Fund. These are Enterprise Ireland terms with their own assessments. PSSF does not secure the next investment for you.
3. Angels and HBAN: choose who you want in the business
An angel invests their own money. Some bring experience and introductions; others mainly bring cash. Establish what the person is offering and how involved they expect to be.
A syndicate invests as a group. The lead investor may help negotiate and organise the round. Find out who decides, who signs and who you will deal with afterwards.
HBAN, the Halo Business Angel Network, is one route to investors. Our angel funding guide covers the financial pack to prepare.
Look for investors whose stage, sector and cheque size fit. Baseline, for example, advertises €100,000 first cheques within its AI-native SaaS and infrastructure focus, including pre-product and pre-revenue companies. Other investors want more commercial evidence.
You can build in Ireland and approach investors abroad. Look for people who understand your market and stage.
Ask what happens after investment. Can they help with customers or hiring? Can they invest again? Speak to founders they backed when things went badly as well as when they went well. Eamon Leonard explores that in his first investor meeting guide.
A good business can still be the wrong investment for a fund. A profitable company providing a good living for its founders may never produce the exit that fund needs.
Keep the business moving while you raise
Sean Mullaney’s Seapoint fundraising account shows the preparation and organisation behind a raise. Build a relevant investor list, arrange meetings and track the next decision.
An introduction can help. So can a well-targeted direct approach or application. “Send us an update” means you still have work to do.
Fundraising takes founder time away from customers, product and staff. Decide who covers that work and keep a cash forecast that allows for a slow close or no close.
Interest, agreed terms and money in the bank are three different stages.
4. Valuation: how much are you selling?
Wanting €1 million does not tell you what the business is worth. Investors will look at the team, product, market and customer evidence, then negotiate a price and the rights that go with it.
Pre-money is the agreed value of the company before the new investment. Post-money is that value plus the new money going into the company.
Here is what a €1 million investment buys at a €4 million pre-money valuation versus a €4 million post-money valuation:
| Example | €4m pre-money | €4m post-money |
|---|---|---|
| Value before investment | €4m | €3m |
| New investment | €1m | €1m |
| Value after investment | €5m | €4m |
| Investor owns | 20% | 25% |
| Existing owners retain | 80% | 75% |
The investor’s percentage is the new investment divided by the post-money valuation. In both cases, the company receives €1 million in cash before fees. The valuation is not its bank balance.
So when someone says “a €4 million valuation”, ask whether that is pre-money or post-money. On these figures, the answer changes how much of the company you sell.
These examples assume new cash for new shares. Include converting notes and any option-pool changes when modelling the full deal.
A higher headline valuation is not automatically a better deal. Compare the ownership, investor rights, cash actually received and expectations for the next round.
An ambitious valuation today can also create a harder hurdle for the next raise. A down round generally means new shares are issued at a lower price than in the previous round. The headline company valuation can obscure that when the share count or rights have changed.
5. First employees: what does “2%” actually mean?
You want someone good. They want more cash than you can pay. Shares or options may help close the gap, but agree exactly what you are offering.
“Two per cent” could mean ownership today or after the next round, with or without the employee pool included. Those can produce very different results.
An option gives the employee a right to buy shares at an agreed exercise price. The grant awards it; vesting determines when it is earned. A cliff delays the first vesting, and the leaver terms govern what happens on departure. Walk through those terms with the person before either of you commits.
An ESOP often means an employee share option plan, although the abbreviation is also used for employee share ownership plans. The option pool reserves capacity for grants; reserving it does not give employees shares.
KEEP, the Key Employee Engagement Programme, can provide favourable Irish tax treatment for qualifying options. Check the company, employee, valuation and option conditions before the grant.
Put the salary, employer costs and equity offer in the same hiring plan. Paying partly in options still leaves a payroll bill.
6. Pre-seed and seed: agree the deal behind the name
Pre-seed and seed are early-stage funding labels. A seed round might pay for product development, a team or a sales process you can repeat. Say where the business is, how much you need and what it will achieve. The amount and terms are negotiated.
A VC, or venture capital investor, invests through a fund. Some funds back the earliest stages; others want an established business. Find out which before spending weeks pursuing them.
You also need to agree how the money goes in:
| Term | What it means for the funding conversation |
|---|---|
| Priced equity round | Investors subscribe for new shares at an agreed price. |
| CLN: convertible loan note | Debt with contractual conversion terms. Check interest, maturity and repayment as well as conversion. |
| SAFE: Simple Agreement for Future Equity | Investor pays now for rights to shares later, usually on a priced funding round. See the example below. |
| ASA: Advance Subscription Agreement | Money subscribed before the shares are issued. Check the conversion events and longstop date. |
| SeedFAST / SeedNOTE | SeedLegals product names for its advance-subscription and convertible-note arrangements. |
SAFE: money now, shares later
A SAFE is a Simple Agreement for Future Equity. The investor pays the company now for contractual rights to shares later. The shares are usually issued when a priced funding round triggers conversion.
For example, €100,000 converting at 80 cent a share buys 125,000 shares. The cap, discount and agreement determine the price; the total share count determines the ownership percentage.
Y Combinator’s standard SAFE has no interest or maturity date. If no conversion or other termination event happens, it can remain outstanding indefinitely. A sale or shutdown has separate provisions; repayment is not guaranteed.
Include the SAFE in the next-round cap table. For an Irish company, have the document and its Irish legal, tax and accounting treatment reviewed before taking the money.
A valuation cap sets a ceiling on the valuation used to calculate conversion under the agreement. If the next round is priced higher, the earlier investor may receive shares at a lower price. A discount can do that too: a 20% discount to a €1 round price means 80 cent a share. If both apply, check which calculation the agreement uses.
An MFN, most favoured nation, clause may let an earlier investor adopt better terms offered later. For example, if you offer a later investor a better conversion discount, the earlier investor may be entitled to it too. Check what the clause covers.
Our convertible loan note guide works through the calculations.
7. Get the cap table for the deal you are actually signing
A cap table, short for capitalisation table, is the ownership record: who holds shares, how many, which class and what percentage they represent.
Using the €4 million pre-money example, suppose the founders own 700,000 shares. The €1 million investor receives 175,000 new shares:
| Holder | Shares before | Ownership before | Shares after | Ownership after |
|---|---|---|---|---|
| Founders together | 700,000 | 100% | 700,000 | 80% |
| New investor | 0 | 0% | 175,000 | 20% |
| Total | 700,000 | 100% | 875,000 | 100% |
The founders still own the same 700,000 shares. Their percentage falls because the company has issued more shares. That is dilution.
A pro-forma cap table shows the proposed position after a deal. The issued-share view counts shares that exist today. A fully diluted view also includes the agreed potential shares from options, pools and converting instruments.
Ask for both the position now and after the whole transaction, including any employee pool.
Now suppose the terms also require a 10% unallocated employee option pool on a post-round fully diluted basis, included in the pre-money capitalisation. The investor still gets 20%.
| Post-round fully diluted ownership | No pool | Agreed 10% pool |
|---|---|---|
| Founders | 80% | 70% |
| New investor | 20% | 20% |
| Unallocated employee option pool | 0% | 10% |
| Total | 100% | 100% |
One share calculation for the pool scenario is 700,000 founder shares, 100,000 reserved option shares and 200,000 new investor shares. The €4 million pre-money value is divided by 800,000 fully diluted shares, giving €5 per share. The investor’s €1 million buys 200,000 shares.
The founders hold 70% of the 1 million fully diluted total. Because the unallocated pool is not issued share capital, they hold 77.78% of the 900,000 shares actually issued.
Both percentages can be correct. Neither tells you, on its own, who controls decisions.
The example excludes existing notes and options. Add any PSSF or other convertible funding using your actual conversion terms.
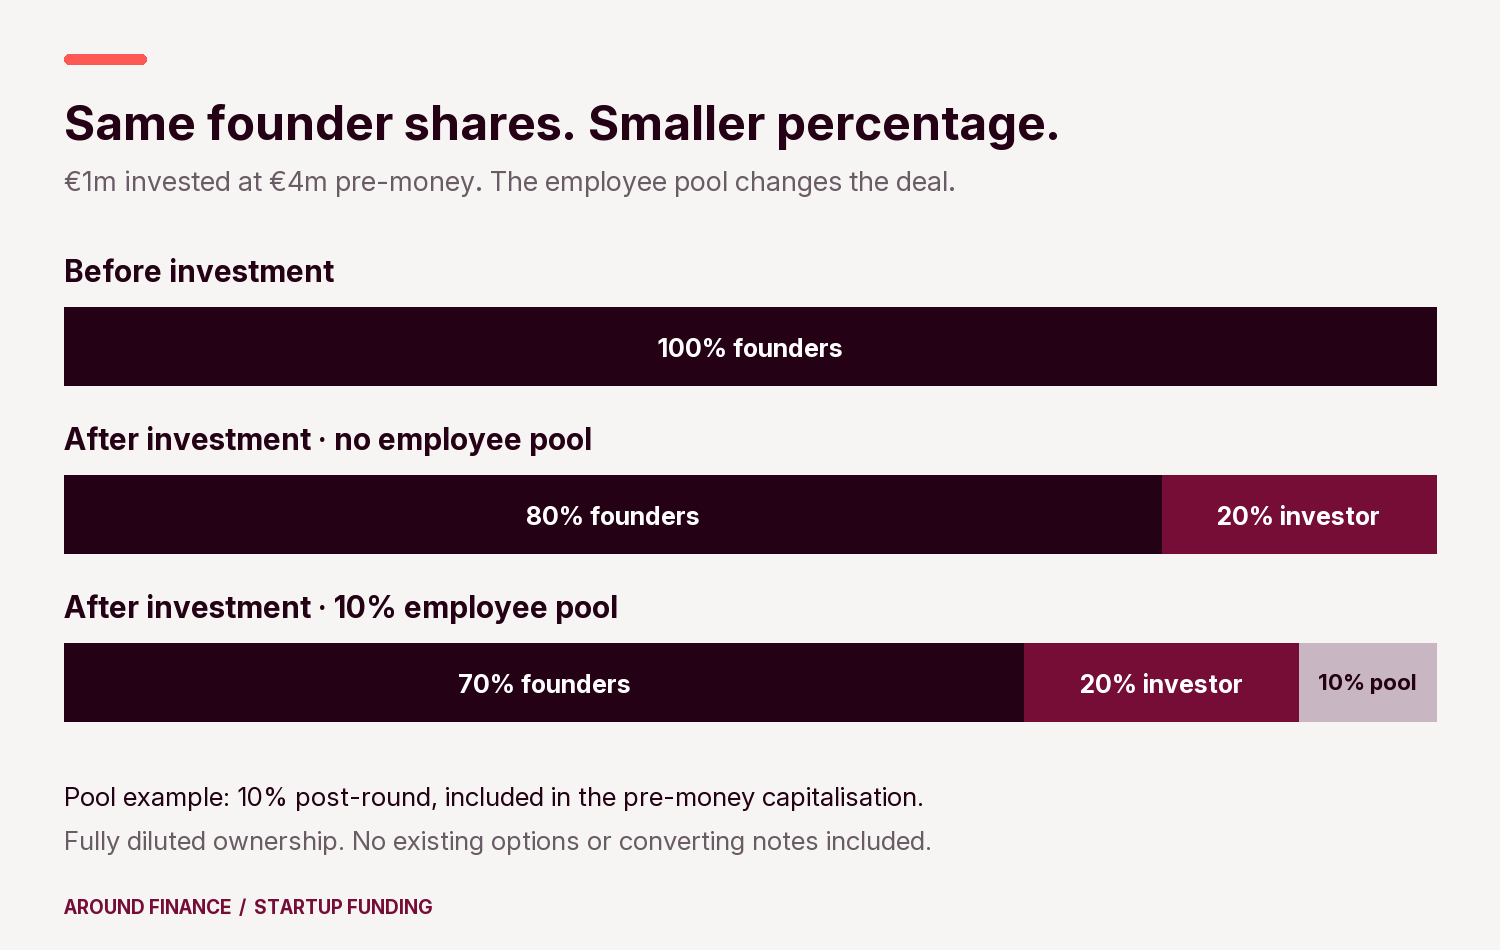
Size the pool around the people you expect to hire. Do not agree a percentage without modelling its effect. Carta explains the pool-timing mechanics; its US legal and tax procedures are separate from Irish requirements.
8. EII, EIS and SEIS: identify whose tax relief is being discussed
EII, EIS and SEIS are tax-relief schemes, separate from the investment instruments explained above. Choosing a SAFE or a loan does not establish eligibility for relief. Keep the Irish and UK schemes separate.
In Ireland:
- EII, also commonly called EIIS, is the Employment Investment Incentive for qualifying investor investment.
- SCI, the Start-up Capital Incentive, concerns qualifying connected or family investment in early-stage companies.
- SURE, Start-Up Relief for Entrepreneurs, concerns qualifying investment by individuals starting their own company.
The investor, company and investment conditions differ. Start with Revenue’s Irish investment-relief guidance. Do not promise relief because someone has called the round “EII”.
EIS is the UK’s Enterprise Investment Scheme; SEIS is its Seed Enterprise Investment Scheme. EMI, Enterprise Management Incentives, is a UK employee share-option regime, separate from those investor reliefs.
Irish founders may hear these when speaking to UK investors or recruits. Irish incorporation alone does not establish UK eligibility. Around Finance handles the Irish-side work; UK treatment needs a UK adviser. HMRC’s investor-scheme overview explains the distinction.
9. Closing the round: a term sheet is not money received
The term sheet sets out proposed terms. Which parts bind you depends on its wording; read exclusivity, confidentiality and costs as well as the valuation.
Due diligence is the investor’s investigation. Your data room holds the supporting financial, commercial and legal records. Prepare current accounts, a cash forecast, the share register and cap table, existing investment documents, customer contracts and records of employee options and intellectual property. Ask the advisers handling the round for their checklist and resolve gaps early.
The subscription agreement deals with the investment. The shareholders’ agreement, or SHA, sets agreed rights and obligations between shareholders. Conditions precedent are matters that must be satisfied before completion. A longstop date is a contractual deadline.
Your solicitor handles the legal documents and approvals. Your financial records and ownership model must agree with them.
Also distinguish primary from secondary investment. A primary subscription puts money into the company for new shares. A secondary sale pays an existing holder for their shares. A round can contain both.
If some of the round is paying out existing founders, say so upfront. Show investors how much money will actually stay in the business. Get the structure checked before agreeing it, particularly if EII relief is involved.
Put the different funding sources on one cash timetable
Founder investment, public support, angels and a fund may all contribute to the raise. They can arrive at different times and carry different conditions.
For each source, record the amount, whether it is committed, the conditions still to be met and when the cash should arrive. An angel expressing interest is not committed funding. Test what happens if a payment is late.
Keep this fundraising schedule alongside the business cash-flow forecast, which includes customer receipts and operating costs. That shows whether you can pay the bills while waiting for investment.
Hiring against the total on a slide can create a payroll commitment before the funding exists.
A grant may reimburse eligible spending after the company has paid it. An R&D tax credit is a separate claim with its own qualifying costs and receipt timetable. Neither should become immediate cash merely because it appears in the funding deck.
Check how public supports interact, including funding the same expenditure. Do not assume every proposed combination meets programme or tax-relief conditions.
The company receives the angel’s investment. Any EII tax relief belongs to the investor and adds nothing to the company’s bank balance.
10. After seed: the money now has to do the work
A raise gives you cash to deliver the plan. Update it for the amount actually received, fees and when people will start. Keep checking whether the spending is producing the progress you promised.
Burn is the cash the business consumes. Runway is how long your cash lasts. At €50,000 monthly net cash use, €600,000 gives you 12 months. Increase that to €75,000 through hiring and you have eight.
Put those dates beside the work. If the evidence for your next round will take nine months, eight months of cash leaves you a problem before you have started the next raise.
Use a dated forecast for payroll, tax, suppliers and customer receipts; the average monthly number can hide a shortfall.
Keep investors informed about cash, progress, what changed and where you need help. Keep the accounts, cap table and option records current so the next raise does not begin with months of reconstruction.
11. Series A and beyond: show what the last money achieved
The next investor will want to see what changed since the previous round. Did customers stay? Did revenue grow? What did it cost to win and serve them? What is the next investment supposed to improve?
Series A, Series B and later labels do not have fixed cheque sizes. For a SaaS company, retention, recurring revenue and customer acquisition costs may be central. The evidence should fit the business.
Hiring more people to repeat a sales process you understand is a different decision from hiring them to discover whether anyone wants the product. Make that clear in the plan.
Model the new shares, converting notes and employee pool top-ups before agreeing terms.
Private equity funds often back more established businesses through growth investment or a buyout. A fund investing in mature companies may be the wrong target for a first pre-seed raise.
A bridge round buys time between funding events. Be specific about what will happen during that time. If the business missed its targets, explain what you have changed.
Venture debt is borrowing, with repayments and conditions. It may also carry warrants, rights to acquire shares. Include those obligations when comparing it with equity.
Another raise is one option. Better margins, customer cash or a slower hiring plan may give you a better result. Decide which route the business can support.
12. What can the investor stop, and who gets paid on a sale?
Owning most of the shares does not necessarily leave you free to make every decision.
A reserved-matters clause might require investor consent before you raise more money, take on substantial debt or sell the company. A board-seat right lets the investor appoint a director. Ask which decisions need a board vote and which need separate shareholder consent.
Preference shares can change who gets paid first. A negotiated liquidation preference might let an investor take the first €1 million of proceeds available to shareholders on a sale before ordinary shareholders receive anything. Whether the investor also shares in the balance depends on the agreed rights.
A waterfall is the calculation showing those payments. Ask for it at a disappointing sale price as well as a successful one. Twenty per cent of the shares does not necessarily mean 20% of the sale proceeds.
Anti-dilution protection can adjust an investor’s conversion rights if a later round prices shares below their earlier investment price, for example €3 instead of €5. Ask what that adjustment does to the founders’ percentage.
A pro-rata participation right might let a 20% investor buy 20% of the new shares offered in a later round. Pre-emption can also apply to transfers: a founder may have to offer shares to existing holders before selling to an outsider.
Drag-along rights can require you to sell if the agreed approval threshold is met. Tag-along rights can let you join another holder’s sale.
Have your solicitor explain these rights using your proposed documents and numbers before you sign.
Learn from other founders without copying their deal
Rekord’s own pre-seed announcement names Point Nine, Hello World, Octopus Ventures, Baseline and angels among its backers. It is an Irish example of investors participating together, rather than a rule that you must finish with one source before approaching another.
Y Combinator, Seedcamp and First Round Review offer useful accounts of preparation, rejection and the choice to raise. Reddit and Hacker News can surface questions other founders struggled with.
Learn how they prepared and made decisions. Their valuations, tax rules and terms belong to their own circumstances. A funding announcement rarely tells you the whole deal.
Before you commit
Put the spending plan, cash forecast and cap table beside each other. Check what you can afford if the round is late, and what everyone will own after the notes, new shares and employee pool are included.
Around Finance provides accounting and finance support for technology companies. We help founders keep reporting, cash forecasts and funding preparation connected to the decisions they are making, working alongside their legal advisers where needed.
If you have a funded growth plan or a credible near-term funding route and need ongoing accounting support, book a Finance Fit Call. For programme eligibility and early development support, begin with the relevant agency or founder programme.
Frequently asked questions
What funding is available to an Irish startup?
Options include founder investment, qualifying grants, loans, PSSF, angel investment and venture capital. The right route depends on the business, its stage and what the money will achieve. A public support may be investment or debt rather than a grant.
Is PSSF a grant?
No. Enterprise Ireland’s Pre-Seed Start Fund provides investment through a convertible loan note. Check the offer’s payment stages, conditions and conversion terms when planning cash and future ownership.
What is the difference between pre-money and post-money valuation?
Pre-money is the agreed value before new investment. Post-money adds the new money. A €1 million investment at €4 million pre-money buys 20%; at €4 million post-money it buys 25%, before other adjustments.
Can an employee option pool dilute founders further?
Yes. In this article’s example, founders retain 80% after investment without a pool, or 70% if a 10% post-round pool is included in the pre-money capitalisation. The agreed pool size and timing determine who bears the dilution.
What happens to a co-founder’s shares if they leave?
Leaving the business does not automatically mean giving up shares. Agree vesting and leaver terms covering which shares must be offered for sale, who can buy them, the price and payment timing. Have the legal documents put those arrangements into effect.